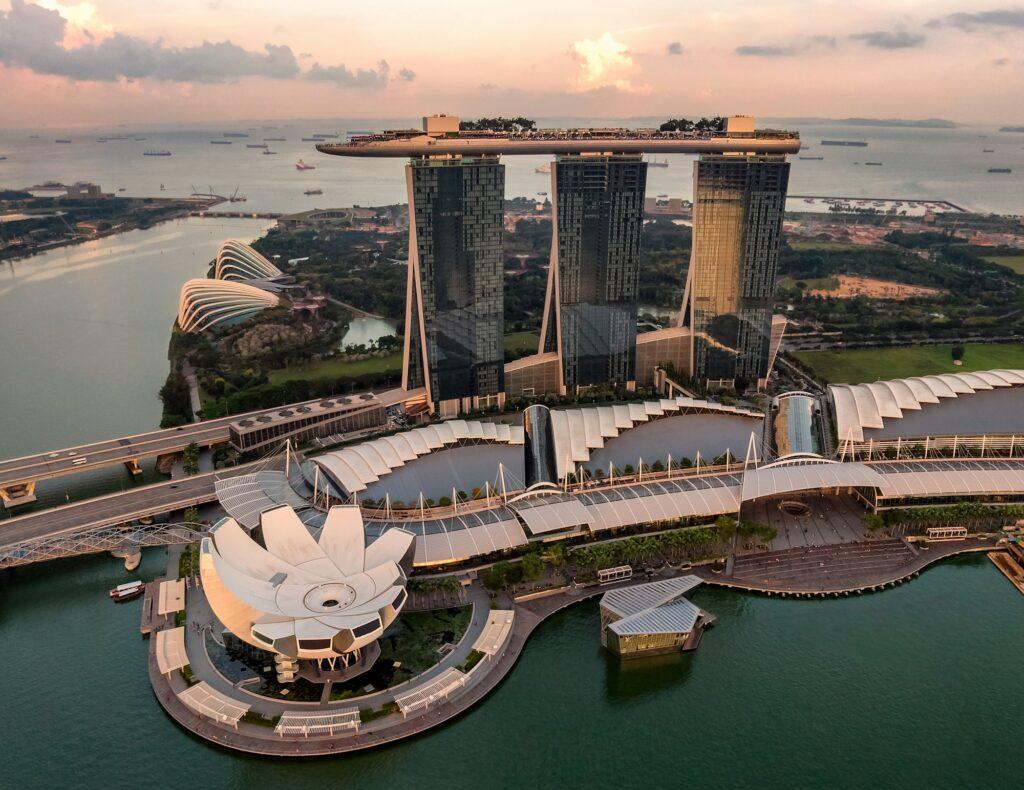
On 31 August 2026, the Monetary Authority of Singapore (MAS) announced a S$220 million commitment — approximately US$174 million — over three years under the renewed Financial Sector Technology and Innovation Scheme (FSTI 4.0). The allocation is intended to strengthen Singapore’s FinTech ecosystem and accelerate the development, adoption and deployment of frontier technologies, with a stated focus on artificial intelligence (AI), distributed ledger technology (DLT) and quantum technology. FSTI 4.0 is the fourth iteration of MAS’s flagship public co-funding scheme, launched in 2015. It is not a private-market “innovation fund”. The previous cycle, FSTI 3.0 (2023–2026), was allocated S$150 million. The new envelope is a material increase and is designed to move the ecosystem from experimentation toward commercialisation and scale.
The Nasdaq Stock Market maintains three distinctive listing tiers: the Nasdaq Global Select Market, the Nasdaq Global Market and the Nasdaq Capital Market. An applicant must satisfy the financial and liquidity tests of the chosen tier, and the corporate governance standards that apply equally across all three. Financial and liquidity thresholds become more demanding as a company moves from the Capital Market to the Global Market and then to Global Select. Meeting every enumerated quantitative test does not guarantee admission. Nasdaq may deny initial listing, or attach additional conditions, where necessary to protect investors and the public interest. This briefing summarises the initial listing standards for the primary common stock or ordinary shares of an operating company, based on the Nasdaq Initial Listing Guide (January 2026). Direct listings, SPACs, closed-end funds and other security types are subject to separate or elevated tests, noted where material.
On July 24, 2026, China’s Ministry of Finance (MOF) and the State Taxation Administration (STA) jointly issued Announcement No. 21 of 2026 alongside Announcement No. 15 of 2026. Taking immediate effect, these landmark regulations clarify the Individual Income Tax (IIT) obligations for mainland China tax residents across the entire lifecycle of offshore trusts (establishment, operation, and liquidation).
Historical tax deferral strategies involving offshore trusts (BVI, Cayman, Jersey, Singapore) are no longer viable. PRC tax authorities now enforce a full “look-through” approach, supported by automated data exchange under the Common Reporting Standard (CRS).
We are pleased to bring you a critical update regarding Hong Kong’s asset management tax landscape. The Inland Revenue (Amendment) (Preferential Tax Regimes for Funds, Family-owned Investment Holding Vehicles and Carried Interest) Bill 2026 was gazetted on 12 June 2026 and introduced into the Legislative Council. Once enacted, these groundbreaking measures will take retrospective effect from the Year of Assessment 2025/26.